VA Loan Assumption in Prince William County: A Seller's Guide to the Low-Rate Advantage
Selling a home in Prince William County this fall comes with an advantage most sellers do not yet realize they hold: if your mortgage is a VA loan, the loan itself may be your home's strongest selling point. With the 30-year fixed mortgage averaging 7.28% for the week ending October 1, 2026, a buyer who takes over your low-rate VA loan at 2.5% to 4% is stepping around today's rates entirely. That is an edge very few homes on the market can offer.
This guide explains how assumption works, why it matters in a military-heavy market like ours, what to know about your entitlement before you market it, and how to position your home for the right buyer.
What Does It Mean to Assume a VA Loan?
VA loans are assumable, which means a qualified buyer can take over the remaining balance of your mortgage at your interest rate and for the rest of your remaining term, instead of opening a new loan at today's rates. The buyer does not have to be a veteran. The mortgage servicer reviews the buyer's credit and income like any loan application, and your loan must be current for the assumption to move forward.
The buyer pays an assumption funding fee of 0.5% of the remaining loan balance, typically within 15 days of closing, with exemptions for service-connected disabled veterans, Purple Heart recipients, and surviving spouses. The servicer may also charge a processing fee capped at $300, or $250 when VA prior approval is needed. Against the rate savings the buyer steps into, those costs are small.
Why should a seller care? Because in a 7% market, your 3% loan is worth real money to the right buyer.
Why Assumption Matters More Than Ever in Prince William County
The math is what makes this story work. On a $400,000 loan balance at 7%, principal and interest run about $2,661 a month. Assume that same balance at 3.5% and the payment drops to roughly $1,796, a saving of about $865 every month. At 2.5%, the saving grows past $1,000 a month. Buyers are paying attention to that math.
National assumable-loan platforms report homes marketed with assumable financing selling faster and, in published examples, pulling premiums above asking price. Industry sources note that roughly ten million FHA and VA loans were originated at rates between 2.5% and 4% during the 2020 through 2022 boom, so a meaningful share of Prince William County listings carry a rate from 2021, not 2026.
Prince William County is one of the strongest places in the country for this story. The county has recorded roughly 1,500 VA purchase loans a year in recent fiscal years. Marine Corps Base Quantico sustains an estimated 25,000 to 30,000 jobs at its gates, Fort Belvoir sits just across the county line, and communities like Dumfries, Triangle, Woodbridge, and Dale City are packed with homes financed by VA loans during those low-rate years. When a Quantico family PCSes out, the buyers may well be another military family PCSing in, and the rate on the loan goes with the house.
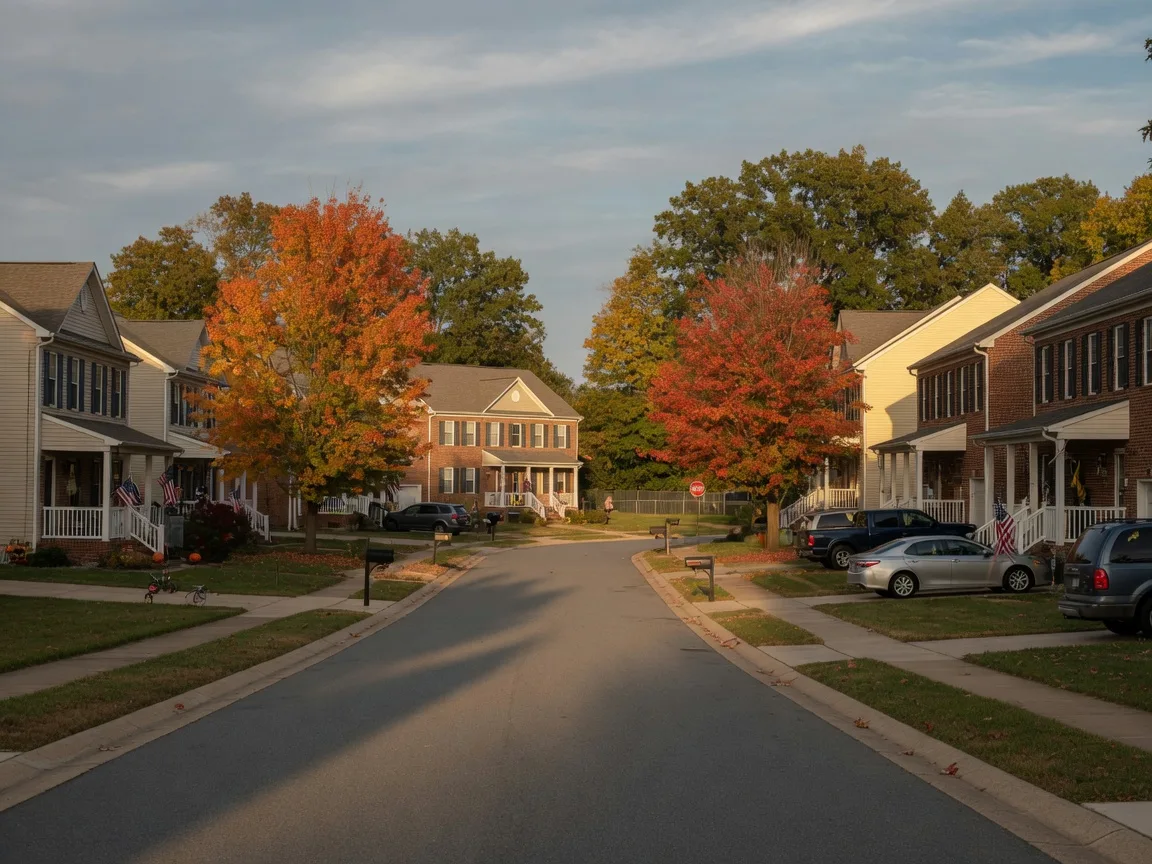
From Dumfries and Triangle to Woodbridge and Dale City, tens of thousands of Prince William County homes were financed with VA loans during the low-rate years.
What Sellers Should Know Before Marketing the Assumption
The detail most sellers miss is entitlement. When a veteran bought with a VA loan, the VA guaranteed a portion of it using the buyer's entitlement. If a non-veteran assumes the loan, your entitlement stays attached to that mortgage until it is paid off, which means you may not be able to use your full VA benefit again in the meantime. If the person taking over the loan is a veteran who formally substitutes their own entitlement, using VA Form 26-8106 and the newer VA Form 26-10291 acknowledgement, your entitlement is restored. This is not a reason to avoid marketing the assumption, but it is a reason to understand exactly how the buyers who come to you are eligible.
The second thing to know: assumption does not lower your sale price. The loan balance stays where it is, so the buyer has to cover the difference between the sale price and the remaining balance with cash or a second mortgage. That makes an assumed loan most attractive when the seller's equity is modest, or when the buyer is bringing substantial cash. For a home bought in 2021 with a 3% loan and modest appreciation, the pieces line up beautifully.
Finally, plan for timing. The servicer's review of the assuming buyer takes time and the assumption is tied to the contract, so the smoothest listings build patience into the closing calendar and stay in touch with the lender from day one.
An assumption keeps the existing mortgage documents in place, rate, term, and balance included, and passes them to the next owner.
How to Position Your Home's Low Rate on the Market
If this sounds like your house, here is the practical checklist I walk sellers through before we list:
- Know your mortgage. Pull your payoff statement and confirm your exact rate and remaining term before you go on the market. You cannot market what you cannot prove.
- Tell your agent the loan is assumable and share the details. Agents who work with military buyers know how to frame this.
- Show the savings math. More sellers are advertising "2.75% assumable VA loan" the way they advertise a new roof, and it gets clicks from qualified buyers.
- Price and show with the right buyer in mind. The assumption still requires underwriting, so a buyer pre-approved by the servicer or a VA-savvy lender is the stronger candidate.
- Be honest about entitlement. A veteran buyer who can substitute their entitlement is the cleanest outcome for you, and an experienced agent will know how to vet that long before an offer arrives.
In more than 25 years in this market, I have rarely seen a single feature move a Prince William County home the way a low-rate assumable loan can in 2026. It rewards preparation.
If you are thinking about selling, let us find out what is written on your mortgage and what it could do for you. Call or text me at 571-377-8777, email GG@MoveMeInVa.com, or schedule a call at your convenience.