FHA Loans in Prince William County: A Plain-English Buyer's Guide for 2026
Yes, FHA loans work well in Prince William County in 2026. The FHA 203(b) loan gets you in with as little as 3.5% down and a 580 credit score, which is why it remains one of the most-used paths into markets like Manassas, Manassas Park, Dale City, and Woodbridge. But before you commit, there are three Prince William specifics worth understanding: this year's loan limits, the cost of FHA mortgage insurance, and how FHA treats the condos and townhomes that make up a big share of our inventory. Here is what I tell every buyer who asks.
The 2026 FHA Loan Limit Here: More Room Than Most People Realize
For 2026, HUD set the FHA loan limit for Prince William County and the rest of the Washington, DC metro area at $1,249,125 for a single-family home, because our region is classified as a high-cost area where the FHA ceiling applies instead of the national floor of $541,287. Practically speaking, the limit is not the constraint for most buyers: the county's median sold price is around $600,000, so nearly every home here falls comfortably inside FHA's range.
Where the higher limit matters is the upper end of the market. In Gainesville, Haymarket, and Nokesville, and at waterfront communities like Potomac Shores, homes regularly price between $700,000 and $1.2 million. An FHA loan can still fund those purchases at the same 3.5% minimum down payment, which surprises buyers who assume the program is only for starter homes.
Down Payment and Credit Requirements: 3.5% Down and a 580 FICO
The FHA 203(b) program needs a minimum 3.5% down payment with a 580 or higher credit score. On a home at Prince William County's recent median of about $600,000, 3.5% is roughly $21,000. If your score falls between 500 and 579, FHA still allows you to buy, but the down payment jumps to 10%. Credit scores below 500 do not qualify, and lenders themselves can set higher minimums than FHA's baseline, so a lender who works with first-time buyers is worth finding early.
FHA is also forgiving about where your money comes from. Down payment and closing costs can be a gift from a family member, which helps many first-time buyers in Manassas and Woodbridge. Your monthly debts are measured against your gross income (many automated underwriting systems cap it near a 43% debt-to-income ratio), and because FHA is a government program, rates are often competitive. In this 7%-rate environment, the low down payment matters: it is the difference between saving for years and buying this spring.
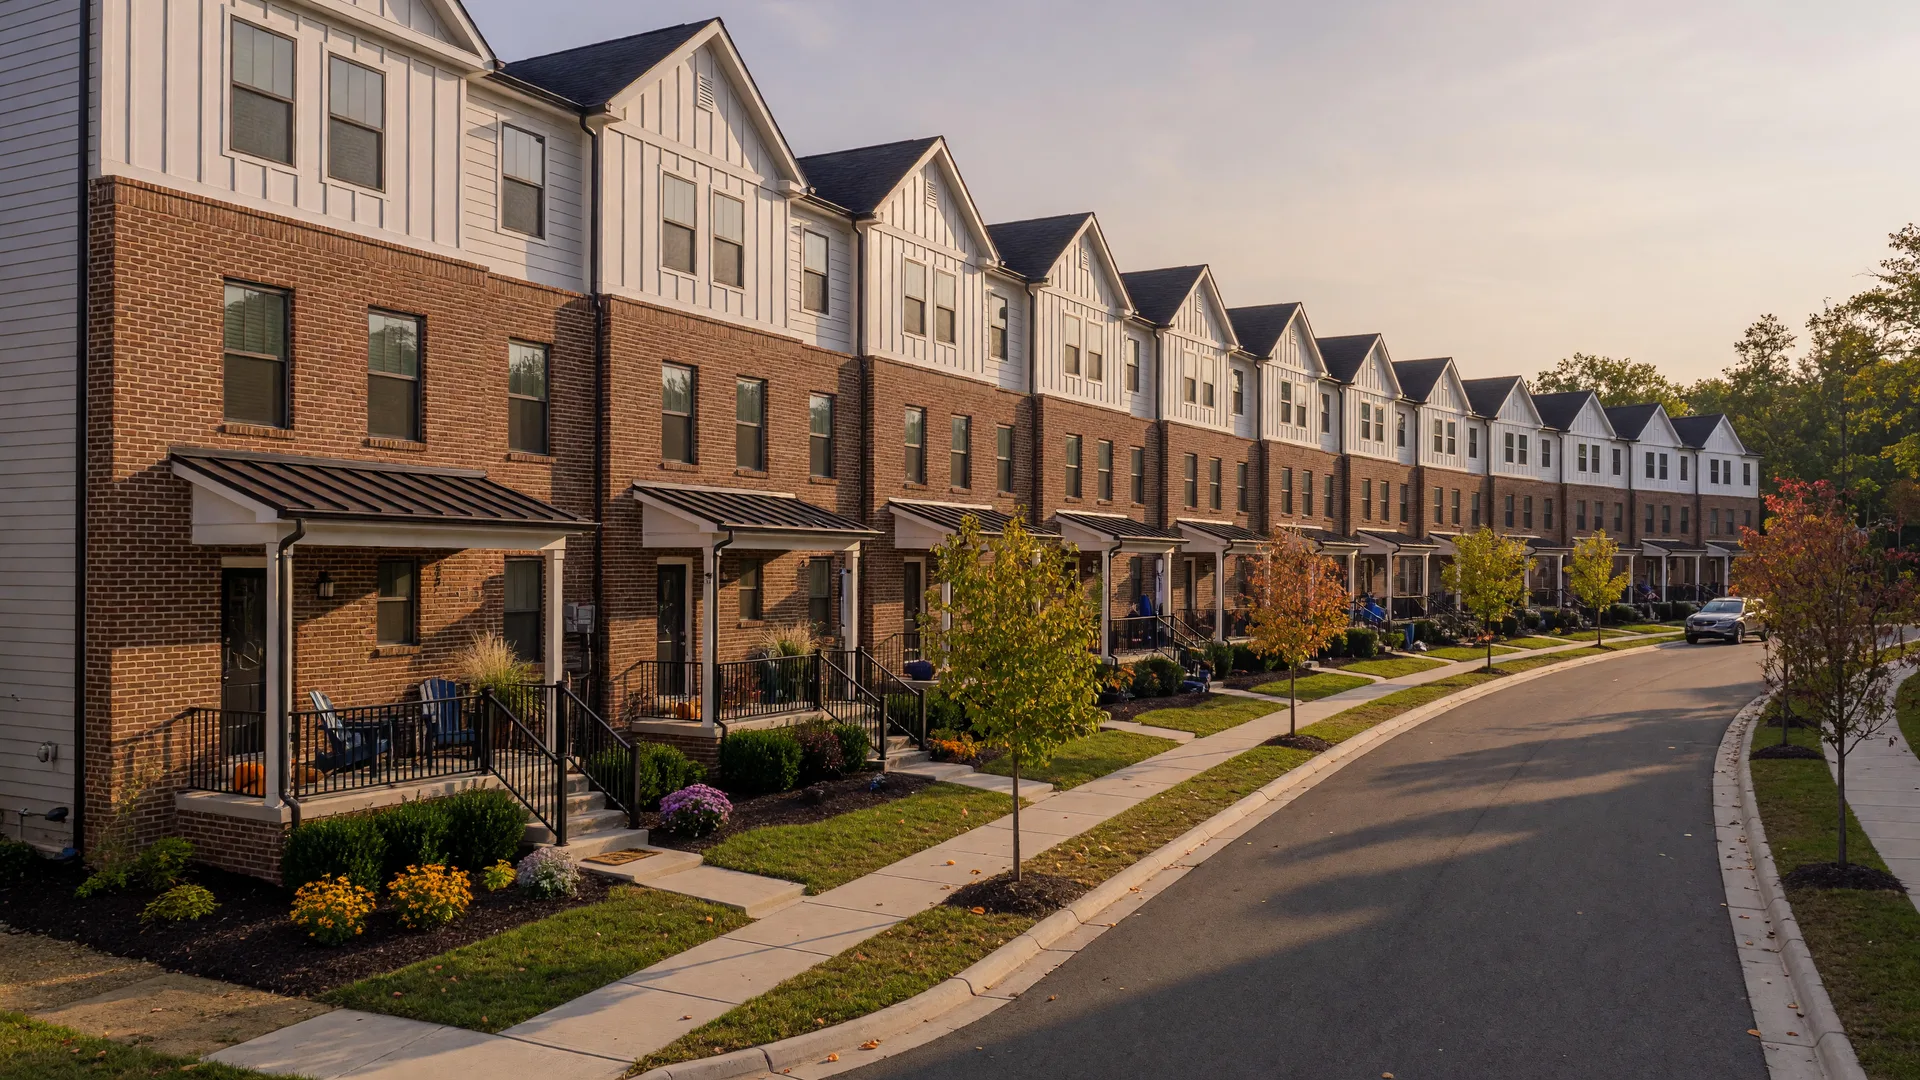
Fee-simple townhomes across Prince William County work fine with FHA financing.
What FHA Mortgage Insurance Actually Costs
The trade-off for FHA's low down payment is mortgage insurance, and it is the number that surprises most buyers. You pay an upfront premium of 1.75% of the loan amount, which is typically financed into the loan rather than paid out of pocket. On a $579,000 loan, that is about $10,133 added to your balance. Then comes the annual premium of 0.55% for the most common 30-year loan with less than 5% down, billed monthly. On that same loan, the annual premium runs roughly $265 a month.
Here is the key difference from conventional private mortgage insurance: on a 30-year loan with less than 10% down, FHA's annual premium stays for the life of the loan. It does not drop off automatically at 20% equity. That is not a reason to avoid FHA, but it is a reason to treat the monthly payment as your real baseline, and it is one reason buyers who can manage a 5% to 10% conventional down payment should compare both routes before writing an offer. I have both conversations with clients every week, and the right answer depends on your cash position and your plans.
FHA, Condos, and Townhomes: Where Approval Matters in NOVA
Most of the townhomes that dominate Prince William County's entry-level market are fee-simple properties in planned developments, which means you own the land beneath your home and the home itself. FHA treats those exactly like detached homes: no extra project approval is needed. That covers a huge share of what first-time buyers actually purchase here, from townhome rows near the Manassas and Woodbridge VRE stations to communities off Linton Hall Road.
The rules change only for true condominium projects, where buyers own a unit in common ownership with a condo association. An FHA buyer needs the project to be FHA-approved, or the specific unit to qualify under FHA's single-unit approval process. That is a step your agent and lender will verify before you commit to a condo floor plan in Woodbridge or Old Town Manassas, and it takes a little longer than a conventional purchase. New construction has its own wrinkle: FHA appraisers check a new home against minimum property requirements, so a builder's spec sheet rarely tells the whole story. None of this is a barrier; it is simply homework, and the right team does it before you commit.
How FHA Fits a 7% Rate Market
Mortgage rates above 7% have made FHA more attractive, not less, because the low down payment lowers the cash hurdle while the rate itself is typically a hair lower than conventional. Two extra tools are worth knowing about. First, an interest rate buy-down, often paid by the seller or builder, can lower your rate for the first year or two and make the payment more comfortable while you settle in. Second, FHA loans are assumable: if the seller's existing FHA loan carries a lower rate, a qualified buyer can sometimes take over that mortgage, subject to lender approval and the equity gap. In a high-rate market, an assumable loan is a genuine advantage, the same logic that makes VA loan assumptions so popular with our military buyers.
Closing day is the payoff for getting your FHA numbers right on the front end.
Stack FHA With Local Help, Then Decide With a Number Crunched
In Prince William County, FHA can be paired with down payment assistance, which pushes the real out-of-pocket cost even lower for qualified buyers. Your credit score, your cash, and your target price range point toward one clear answer, and you should not guess: a lender licensed in Virginia and familiar with local FHA limits can run the exact scenario in minutes. The market here is stable, with a median around $600,000 and inventory slowly rebuilding, which gives FHA buyers more leverage than they have had in years.
Financing is the foundation of every offer, but it is not the whole strategy. The FHA buyers I represent win homes because we pair a realistic pre-approval with a local offer strategy: the right earnest money, the right contingencies, and a listing agent who knows FHA deals close cleanly. If you are thinking about buying anywhere in Prince William County, Manassas, or Manassas Park, let us talk through whether FHA is your smartest path. I will connect you with a lender I trust, walk you through the numbers in plain English, and be looking out for your best interests from the first visit to the final walkthrough, like family.
All the best.